Yes — hitting a deer is covered by auto insurance, but only under the comprehensive portion of your policy, not the collision or liability portions. In New York State, comprehensive coverage is optional. Drivers who carry only the state-required liability minimums have no coverage for deer damage to their own vehicle. If you have comprehensive coverage, a deer strike is a not-at-fault claim and your comprehensive deductible applies.
Deer strikes are among the most predictable vehicle damage events that upstate New York drivers face. According to the New York State DMV, there were 32,287 crashes involving deer statewide in 2024 — with November the worst month at 5,854 deer struck. The Capital District sits at the center of some of the state's highest deer densities: the Hudson and Mohawk river corridors, the Helderberg escarpment, and the agricultural edges around Clifton Park, Bethlehem, Guilderland, and East Greenbush push deer across active commuter routes — Route 9, Route 9W, Route 20, and Route 4 — throughout the year. Every autumn, collision shops across Albany, Schenectady, Troy, and Saratoga Springs handle a surge of vehicles with crumpled hoods, shattered headlamps, and significant hidden structural damage beneath panels that appear only mildly dented.
Why the Capital District Is High-Risk Deer Territory
According to State Farm's annual animal-collision analysis, New York drivers face approximately a 1-in-185 chance of an animal collision claim, ranking the state 33rd nationally. The Capital District's mix of suburban growth, river valleys, and dense surrounding woodland keeps local risk consistently high: Albany, Saratoga, Rensselaer, and Schoharie counties all sit alongside established deer movement corridors, and the continuing expansion of suburbs into former farmland and woodlots gives deer more road crossings at unpredictable hours.
Two periods carry the highest risk. The primary peak runs from mid-October through late December. The autumn rut — when bucks pursue does with little regard for traffic — drives the largest share of deer collisions, and state data confirms November is consistently the worst month: 5,854 deer were struck in November 2024, compared with 4,050 in October and 3,624 in December, according to the NY DMV. A secondary, smaller spike occurs in May and June when yearling deer disperse from their birth ranges. Sunrise and sunset are the most dangerous windows year-round, though rut-driven autumn collisions can happen at any hour.
Does Insurance Cover Hitting a Deer in New York?
A deer strike is covered under the comprehensive portion of your auto insurance policy — sometimes labeled "other-than-collision" — not the collision portion. Comprehensive covers damage from events outside a crash with another vehicle: fire, theft, vandalism, hail, floods, and animal contact. Because a deer runs into the road, a deer strike qualifies as a comprehensive claim even when you had no chance to avoid the animal.
The distinction between comprehensive and collision matters because they often carry different deductibles, and some drivers carry one but not the other. Most New York policies are written with comprehensive deductibles of $250 to $1,000. Your out-of-pocket cost on a deer claim comes down to one number: your comprehensive deductible.
New York is a no-fault state, but that designation applies to personal injury coverage (PIP), not to property damage. Your vehicle damage from a deer strike flows through your comprehensive coverage regardless of the state's no-fault rules. Liability coverage — the coverage that pays for damage you cause to other parties — does not apply to a deer strike at all.
What if You Swerved and Missed the Deer
If you swerved to avoid the deer but did not make contact with the animal and struck a guardrail, tree, or other fixed object instead, that damage is typically filed as a collision claim, not a comprehensive claim, even though a deer in the road caused the maneuver. If you struck both the deer and a secondary object, the claim may be split, or the insurer may apply the coverage that matches the greater share of the damage. Discuss the exact sequence of events with your insurer carefully, because the coverage type determines which deductible applies.
What if You Don't Have Comprehensive Coverage
Drivers who carry only the New York liability minimums have no coverage for deer damage to their own vehicle. If you lease or finance your car, your lender almost certainly requires comprehensive coverage — but if you own your vehicle outright and dropped comprehensive to cut costs, a deer strike comes entirely out of pocket. Before autumn, drivers in deer-heavy corridors who lack comprehensive should run a comparison quote: given the frequency of deer strikes in the Capital District and typical repair costs for a mid-severity front-end impact, the annual premium for comprehensive coverage often costs less than a single claim.
Should You File a Claim or Pay Out of Pocket?
Even with comprehensive coverage, filing is not always the right move for minor damage. The calculation is straightforward: if the repair cost is only slightly above your deductible — say, $700 in repairs against a $500 deductible — you gain just $200 from your insurer while adding a claim to your record. A single not-at-fault comprehensive claim rarely raises New York rates, but insurers vary, and some do note the claim history even without a surcharge. For damage clearly well above your deductible, file. For marginal cases, ask your agent how your specific carrier treats comprehensive claims before you decide. Because deer damage often looks minor but costs significantly more once a technician disassembles the front end, most Capital District drivers who have struck an adult deer at road speed will find their repair costs well above any typical deductible.
How Long Do You Have to Report Hitting a Deer to Your Insurer?
Most insurers want notification within 24 to 48 hours of the incident. Major carriers including State Farm, GEICO, and Progressive all state that reporting as soon as possible is the expectation, and delays of more than a few days risk a claim dispute: an insurer may question whether additional damage occurred after the event, and scene documentation becomes harder to verify. Report to your insurer before you arrange a tow if you can — most carriers have preferred towing arrangements and can dispatch directly, potentially reducing your out-of-pocket towing cost.
Filing the Claim Correctly
As soon as it is safe to do so, photograph the damage to your vehicle, the road, any debris, and the surrounding area. If the deer is still present, photograph it — this documentation supports your claim and removes ambiguity about what caused the damage. Then call local law enforcement to request a police report. In rural stretches of Albany, Saratoga, Rensselaer, or Greene counties, the responding agency may be the county sheriff's office or the New York State Police. Get the report number before leaving the scene.
Under New York State law, any motor vehicle accident involving property damage exceeding $1,000 requires the driver to file a Report of Motor Vehicle Accident (Form MV-104) with the DMV within ten days. Given that deer damage routinely costs several thousand dollars to repair, assume this threshold will be met and file accordingly. The form is available at dmv.ny.gov. Failure to report when required can result in license suspension, so do not skip this step even if your insurer does not mention it.
What Actually Happens to a Car When It Hits a Deer
Deer are heavier than they look. An adult whitetail doe in the Capital District typically weighs 90 to 130 pounds; bucks in rut commonly reach 150 to 200 pounds. At 45 miles per hour, the kinetic energy transferred to your vehicle's front end is substantial and does not distribute evenly across the structure. Here is what collision repair technicians across the Capital District find most often when they disassemble a deer-strike vehicle.
Bumper Covers and Energy Absorbers
The plastic bumper cover is usually the first contact point and the first to show visible damage: cracks, tears, and displacement from its mounting clips. What the bumper cover does not reveal is damage to the foam or plastic energy absorber behind it, or to the steel reinforcement bar behind that. These components are engineered to deform in a controlled way so that critical mechanical and structural components behind them absorb less energy. Deformation means replacement, and replacement requires removing and inspecting every layer — which is where additional damage becomes visible.
Hood, Fenders, and Headlights
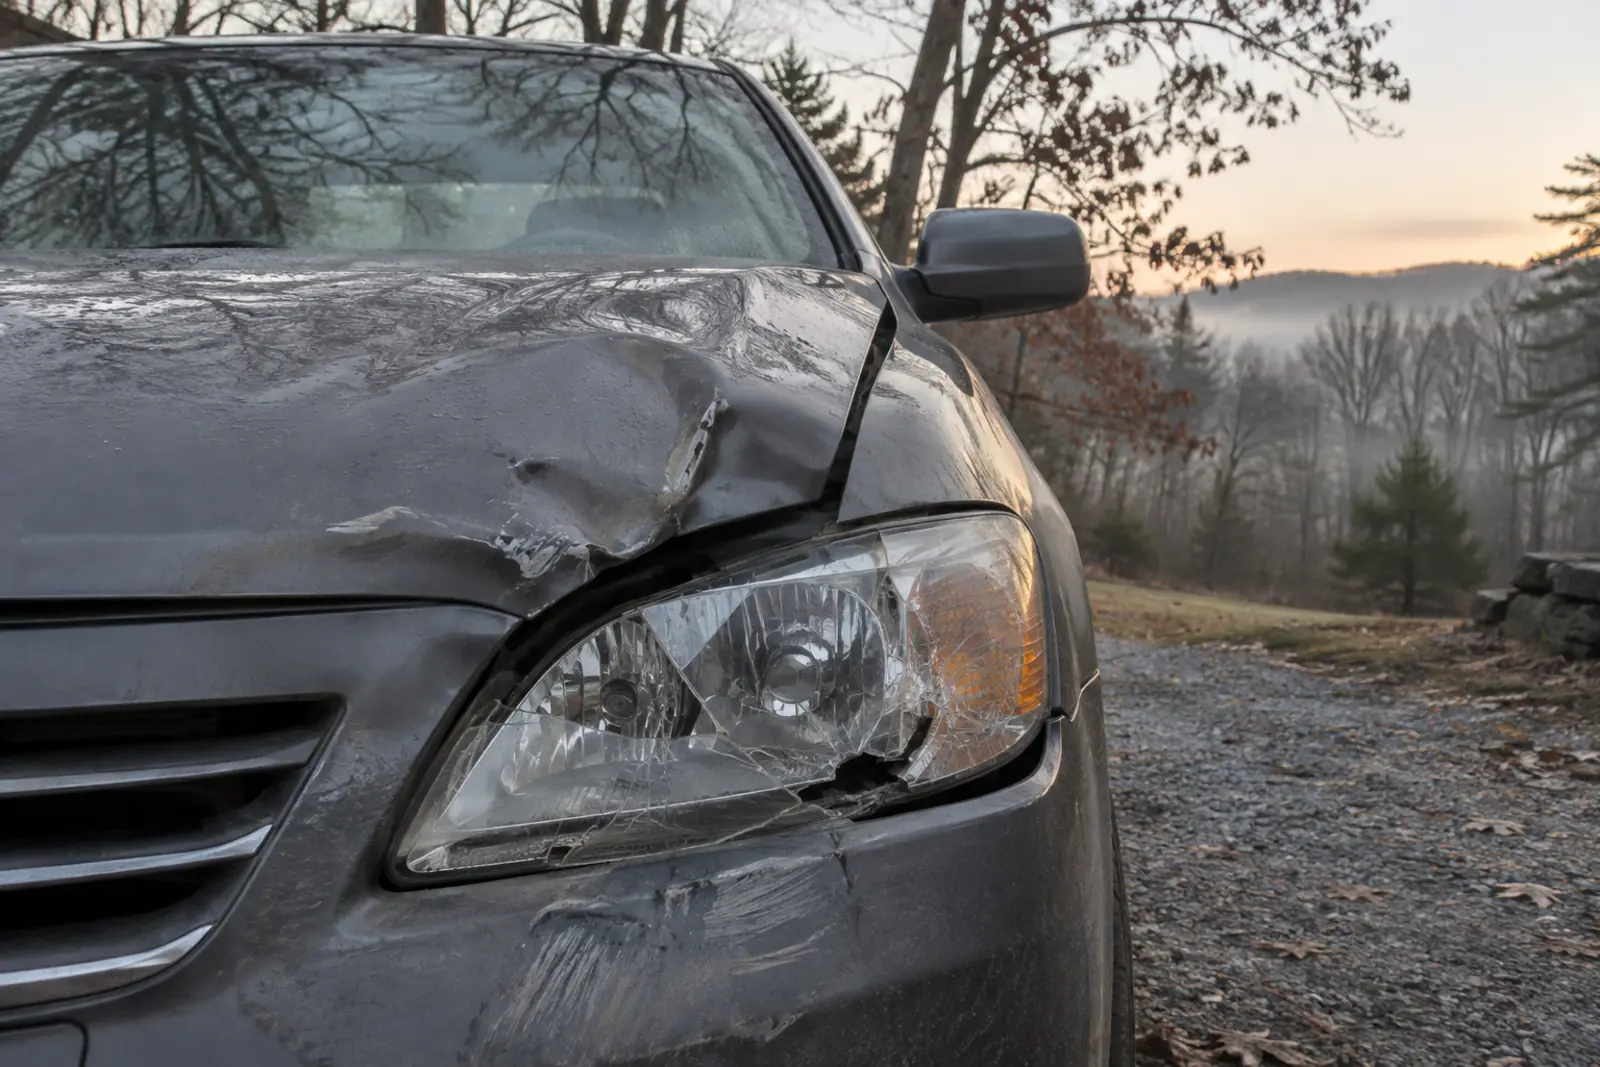
When a deer is struck at speed, the animal's body commonly rotates up onto the hood as momentum carries it forward. This impact pattern explains why so many deer-strike vehicles arrive at the shop with a crumpled hood, bent fenders, and shattered headlamp assemblies even when the driver's primary sensation was a front-end hit. Modern headlamp assemblies — especially units with LED projectors, adaptive lighting motors, and integrated forward-facing cameras — can cost $800 to $2,500 or more per side before labor. A strike that looks like a bumper-only job at the scene can become a $5,000 to $8,000 estimate once the technician and adjuster conduct a complete inspection.
Radiator, A/C Condenser, and Cooling System
Behind the grille opening sits the air conditioning condenser and, directly behind it, the engine radiator. Both are relatively thin heat-exchange units with delicate aluminum fins. Even moderate front-end intrusion — the kind that barely dents the bumper reinforcement — can push grille structure far enough rearward to puncture or crush one or both components. A leaking radiator may not make itself obvious immediately; coolant loss can be gradual, and a driver who moves the vehicle risks overheating the engine before warning lights register the problem. A punctured A/C condenser results in refrigerant loss that becomes apparent only when the driver runs the air conditioning. A qualified technician will pressure-test the cooling system and inspect the refrigerant charge as part of any thorough deer-damage estimate. If your shop skips these steps, ask why.
Wiring Harnesses and Electronic Modules
Modern vehicles route substantial wiring through the front bumper zone for fog lights, parking sensors, forward-facing cameras, and radar modules. Deer strikes that deform the front fascia frequently damage these harnesses as well. Wiring harness damage can produce intermittent electrical faults that do not surface until days or weeks after the repair if the technician does not trace and test every affected circuit during the inspection and repair process. A shop that returns your vehicle with warning lights cleared but harness damage unaddressed is not completing the repair.
Core Support and Frame Rails
The core support is the welded steel structure that holds the radiator, condenser, headlamp assemblies, and hood latch. It is also one of the first structural members to receive crash energy from a front-end impact. Core support damage — bends, cracks, or displaced mounting points — affects how the front end aligns and how it will perform in a subsequent impact. Frame rail damage, which occurs in higher-energy strikes, affects the vehicle's fundamental geometry and must be measured and corrected on a frame alignment rack before any cosmetic or mechanical repair is finalized. A shop that repairs sheet metal without first verifying structural dimensions is cutting a corner that matters to your safety.
Windshield, Roof, and A-Pillars
When a deer is struck at highway speeds, the animal can travel over the hood and into the windshield. This is less common than front-end damage, but the results are severe: windshield replacement, A-pillar damage, roof panel damage, and in some cases airbag deployment triggered by pressure sensors in the windshield surround. These vehicles require particularly careful structural measurement before any cosmetic work begins.
The "It Doesn't Look That Bad" Problem
Deer-strike damage is notorious among collision repair professionals for looking less severe than it is. Sheet metal and plastic are the surfaces you see, and modern vehicle design deliberately manages crash energy by directing deformation into components that sit behind visible surfaces — components engineered to collapse so that occupants and mechanical systems behind them are protected. A hood that is only slightly crumpled may be sitting on a bent core support and a damaged radiator. A bumper that looks merely scuffed may conceal a crushed energy absorber, a cracked reinforcement bar, and compressed condenser fins.
This creates a practical problem with insurance estimates. An initial estimate written from photographs or a cursory visual inspection will almost always be followed by a supplement — meaning the shop will find and document additional damage once panels are removed and underlying components inspected. Supplement estimates are normal and expected in deer-damage repairs. A shop that tells you upfront that a supplement is likely is being honest; an insurer or shop that presents a very low initial estimate as comprehensive and final is probably not conducting a thorough inspection. For how supplement claims are handled with insurers, see the guide to supplement claims in the Capital District.
ADAS components deserve particular attention in this context. Front-facing radar units, camera modules, and ultrasonic sensors mounted in or behind the grille area are frequently displaced or damaged in deer strikes. Even when the sensor housing appears intact, the mounting bracket may be bent enough to throw off calibration. A vehicle whose ADAS sensors are out of calibration after a repair may have lane-keeping assistance, automatic emergency braking, or adaptive cruise control systems that behave incorrectly — and the driver may not discover the problem until the system is needed in an emergency. Any deer-strike repair that touches the front bumper or grille area on a late-model vehicle should include a post-repair ADAS scan and any required calibrations. What ADAS calibration involves after a collision is covered in a separate guide.
The Repair Process for Deer Collision Damage
A proper deer-damage repair follows the same disciplined sequence as any other collision repair job, but the supplement-heavy nature of these claims makes thoroughness at the inspection stage especially important.
Disassembly and Full Damage Assessment
The repair starts with removing damaged panels and covers to expose underlying structure. This is where supplements are generated — not as a surprise or a negotiating tactic, but as the natural result of doing what a visual estimate could not. A reputable Capital District shop will photograph all damage found during disassembly and share those photographs with your insurer as part of supplement documentation. You are entitled to see this documentation.
Structural Measurement and Correction
If frame rails or the core support show damage, the vehicle goes onto a measuring system — either a dedicated frame rack or a computerized laser or ultrasonic measuring tool — to verify dimensions against manufacturer specifications. No cosmetic repair should begin until structural measurements confirm the vehicle is within tolerance or it has been corrected to specification. This step cannot be skipped or estimated visually.
Mechanical Repair
Cooling system pressure tests, A/C refrigerant checks, wiring harness inspections, and drivetrain checks (when there was undercarriage contact) happen in parallel with structural work. Parts are ordered once the full scope of damage is confirmed — ordering parts before disassembly in a deer-strike job often means ordering the wrong parts after the supplement changes the repair scope.
Panel Replacement and Paint
New panels are fitted, aligned, and prepared for paint. Color matching on modern vehicles — including multi-stage metallics, tri-coat pearls, and manufacturer-specific tinted clears — requires spectrophotometer color reading, test sprays, and careful blending to adjacent panels. A shop that skips proper color matching will leave your vehicle with a visible repair line. That outcome depreciates the vehicle and signals that the same shortcuts may have been taken in less visible steps of the repair.
Post-Repair Calibration and Verification
Before the vehicle is returned, any replaced or repositioned ADAS components should be scanned and calibrated per the vehicle manufacturer's requirements. Some calibrations are performed statically in the shop; others require a dynamic road drive under specific speed and distance conditions. The shop should provide written documentation of any calibrations performed and the results.
Working With Your Insurance Company on a Deer Strike Claim
New York State law gives you the right to choose any licensed collision repair facility to perform repairs on your vehicle. Your insurer may recommend or suggest a "direct repair" shop — a facility that holds an agreement with the insurer to process claims through a streamlined channel. You are not required to use that shop. When insurers present their preferred shop as the convenient or default option, that practice is called steering, and the convenience benefits the insurer, not necessarily you.
Choosing a shop that you trust — one familiar with your vehicle's make, holding relevant manufacturer certifications, and willing to document and argue for a complete repair scope — protects your interests better than defaulting to whichever facility an insurer's app suggests. For help evaluating shops, see how to choose a collision repair shop in the Capital District.
Rental Coverage During Repairs
Many comprehensive policies include rental reimbursement coverage, but the daily limits — often $30 to $50 per day — may not reflect current rental car rates in the Albany area, which can run significantly higher for comparable vehicles. Review your rental coverage terms before the repair begins so you are not caught off guard by the gap between your reimbursement cap and actual costs. If your repair involves a supplement process, parts delays from supply chain backorders, or calibration requirements, the total rental period can extend well beyond what most drivers expect. The guide to rental car coverage during collision repair explains how to get the most from that benefit.
Total Loss Considerations
If the repair cost approaches or exceeds the actual cash value of your vehicle, your insurer may declare it a total loss. New York uses actual cash value rather than replacement cost for total loss settlements. If you believe the insurer's ACV calculation undervalues your vehicle — for example, if comparable vehicles in the Capital District market are currently selling for more than the settlement offer — you have the right to negotiate and to provide comparable sales data as evidence. See the guide to total loss claims in New York for how to build that case. Researching recent sales of the same year, make, model, trim, and mileage in the Albany-Schenectady-Troy market before accepting any settlement offer is time well spent.
What to Do in the Immediate Aftermath of a Deer Strike
- Move to safety first. If the vehicle is drivable and you are on a highway or rural road, move it completely off the travel lanes to the shoulder or a safe pullout before assessing damage or making calls. Activate your hazard lights immediately.
- Do not approach the deer. A deer that appears dead may be stunned and can thrash violently when someone approaches. An injured deer is unpredictable and can cause serious injury. Stay in your vehicle or well clear of the animal.
- Check the vehicle before driving further. Look under the vehicle for fluid leaks — coolant is often green, orange, or pink; differential and transmission fluid tend to be darker. Check that the hood is fully latched. If headlights are damaged, fluids are leaking, or any warning lights are active, the vehicle may not be safe to drive and should be towed. Driving with an active warning light after a deer strike risks adding engine or mechanical damage that may not be covered under the original claim.
- Call 911 or the appropriate non-emergency line. In Albany County, Saratoga County, Rensselaer County, and surrounding counties, the responding agency may be local police, the county sheriff, or the New York State Police depending on jurisdiction. Get the report number before you leave the scene.
- Document everything with your phone. Photograph the vehicle damage, the road, the surrounding area, and the deer if it is present. Photograph any skid marks. Note the exact time, GPS location, weather conditions, and lighting.
- Call your insurer to open a comprehensive claim — ideally within 24 to 48 hours. Do this before arranging a tow if possible — many insurers have preferred towing arrangements and can dispatch directly, which may reduce your out-of-pocket towing cost. File Form MV-104 with the NY DMV within ten days if property damage exceeds $1,000 (available at dmv.ny.gov).
- Have the vehicle inspected by a qualified shop before assuming it is safe to drive. Even when a car starts and moves normally immediately after a deer strike, hidden radiator damage, condenser damage, or wiring issues can cause a breakdown or overheating miles down the road.
Frequently Asked Questions
Does insurance cover hitting a deer if I only have liability?
No. Liability coverage pays for damage or injury you cause to others and does not cover damage to your own vehicle. Only comprehensive coverage — an optional add-on in New York — covers deer damage to your car. If you financed or leased your vehicle, your lender almost certainly required you to carry comprehensive, so check your policy documents before concluding you have no coverage.
Will a deer strike claim raise my insurance rates in New York?
A comprehensive claim is generally treated as a not-at-fault event and does not trigger a surcharge the way a collision claim might. However, policies vary, and some companies will note the claim in your history even without a rate surcharge. Ask your agent how comprehensive claims affect your specific rate tier before filing, so you can make an informed decision if the damage is minor and near your deductible.
How long do I have to report hitting a deer to my insurance company?
Most insurers recommend reporting within 24 to 48 hours. Waiting longer risks a dispute about whether additional damage occurred after the event. Separately, New York requires you to file Form MV-104 with the DMV within ten days if property damage exceeds $1,000 — a threshold that virtually every deer strike involving an adult animal will meet. Report to your insurer and file the DMV form promptly; the two are separate requirements.
What if I swerved to avoid the deer and hit a guardrail or tree instead?
If you did not make contact with the deer itself, the damage is typically filed as a collision claim rather than a comprehensive claim, even though an animal in the road caused the maneuver. If you struck both the deer and a secondary object, the claim may be split between comprehensive and collision, or filed under the coverage that applies to the greater portion of the damage. Discuss the exact sequence of events with your insurer carefully, because the coverage type determines which deductible applies to your out-of-pocket cost.
The shop found a lot more damage than the insurance adjuster estimated — is that normal?
Yes, and it is expected in deer-strike repairs. Supplement estimates are the standard outcome when front-end impacts hide damage behind panels and inside the engine compartment. A reputable shop will document all additional damage with photographs and a written supplement, submit it to your insurer, and receive written approval before proceeding with the additional work. You should not be held responsible for covered damage that was hidden until disassembly, as long as the shop properly documents and submits the supplement to your insurer.
Should I skip filing a claim and pay for minor deer damage out of pocket?
If repair costs are only slightly above your deductible, paying out of pocket can make financial sense — you gain little from your insurer while adding a claim to your record. The complication with deer damage is that "minor" is rarely what it appears at the scene: a bumper with modest surface damage commonly conceals a crushed energy absorber, a cracked reinforcement bar, and compressed condenser fins that only become visible once a technician disassembles the front end. Get a professional estimate before deciding; in most Capital District deer strikes involving an adult animal at road speed, the final repair cost is well above a typical comprehensive deductible.
Do I need a police report to file a comprehensive claim for a deer strike in New York?
New York does not legally require a police report for every single-vehicle deer strike, but most insurers will ask for one, and it substantially strengthens your claim documentation. Without a report, an insurer may request additional verification that the damage was caused by animal contact rather than another type of incident. File the report even when you believe the damage looks minor — the full scope of deer damage is rarely apparent at the scene, and the cost almost always exceeds $1,000, which triggers the NYS DMV reporting requirement regardless.